Oil and gas mineral royalties are a contractual share of oil or natural gas production, or its value, paid to the party entitled to that royalty. Understanding the ownership documents, lease terms, and payment calculation explains why two interests with the same royalty rate can generate very different income.
This guide explains mineral rights and royalty interests, common royalty fractions, payment statements, deductions, taxes, and the factors that affect how long income continues. The examples are hypothetical and illustrate calculations rather than expected earnings.
⚠️ IMPORTANT LEGAL DISCLAIMER: The information provided on this page is for general informational purposes only and does not constitute legal, financial, or investment advice. Oil and gas laws, mineral rights regulations, and royalty structures vary significantly by state and jurisdiction. While we strive to provide accurate and up-to-date information, no guarantee is made to that effect, and laws may have changed since publication.
You should consult with a licensed attorney specializing in oil and gas law in your jurisdiction, a qualified financial advisor, or other appropriate professionals before making any decisions based on this material. Neither the author nor the publisher assumes any liability for actions taken in reliance upon the information contained herein.
Key takeaways
-
- Mineral ownership and a royalty interest provide different rights. Owning the surface alone does not establish entitlement to royalties.
- Oil and gas mineral royalties generally exclude drilling and operating costs, but taxes and legally permitted post-production charges can affect the amount received.
- A lease royalty percentage is different from the payment decimal for a particular well or unit.
- Common fractions include 1/8, 3/16, 1/5, and 1/4. None establishes a universal national average.
- Production, realized prices, ownership allocation, deductions, and accounting adjustments influence each payment.
- Lease duration, well life, and the duration of a separately conveyed royalty interest are different questions.
What are oil and gas mineral royalties?
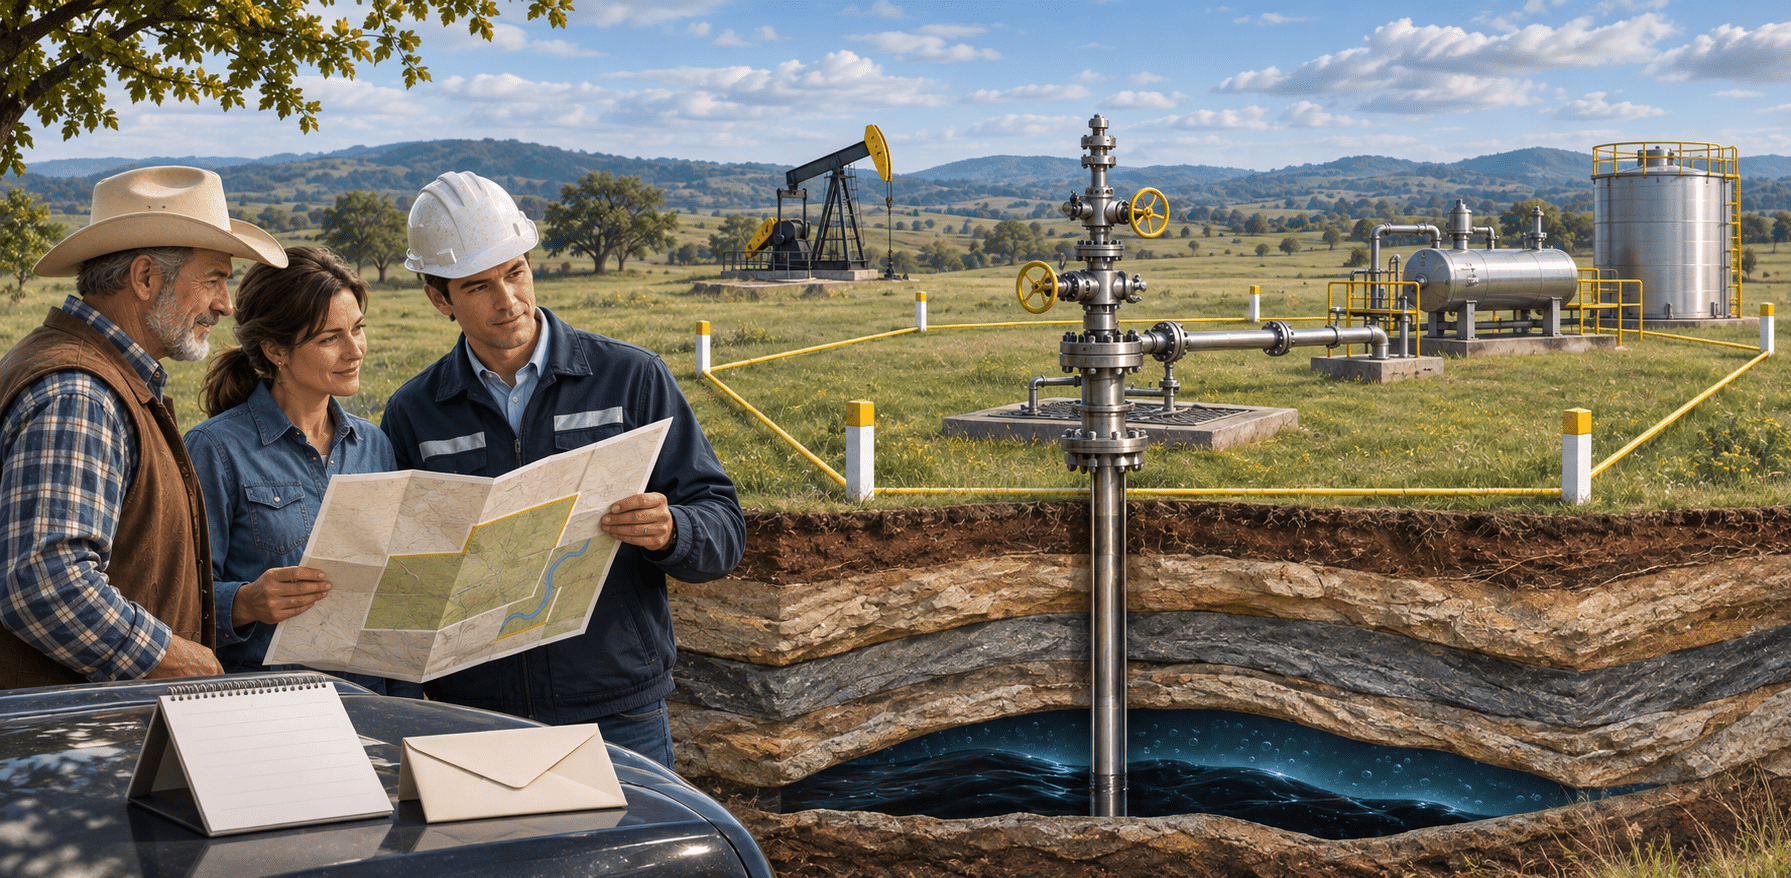
A royalty gives its holder a defined economic share of covered production. In many private leases, that share is paid in money after oil, gas, or related products are sold. Some agreements also address taking production in kind, meaning receiving the product itself instead of sale proceeds.
The obligation comes from the governing lease, deed, assignment, or other instrument, together with applicable law. A royalty is generally tied to production or its agreed value rather than the operator’s accounting profit. A well does not have to recover its drilling investment before an ordinary lessor royalty becomes payable under the lease.
The phrase also differs from a lease bonus. A bonus is consideration for granting a lease, while a production royalty depends on production covered by the agreement. An unsuccessful or undeveloped lease can therefore produce a bonus without generating ongoing royalties. Mississippi State University Extension explains this distinction in its introduction to oil and gas leasing.
Understanding mineral rights and royalty interests
Mineral rights are property rights associated with specified minerals beneath a tract. They can be separated from surface ownership and divided among multiple parties. Depending on previous conveyances, the bundle may include development rights, leasing authority, and rights to certain payments. Cornell’s Legal Information Institute provides a general definition of mineral rights.
A royalty interest is narrower: it provides an economic share of production without necessarily conveying the right to negotiate a lease or operate a well. The distinction between mineral rights and royalty interests matters when reviewing a deed, an inheritance, or an offer to purchase only part of an asset.
A lessor’s royalty is reserved under a lease. A nonparticipating royalty interest, often called an NPRI, is generally carved from the mineral estate and normally carries no executive leasing right or right to lease bonuses and delay rentals. The creating document determines its scope.
An overriding royalty interest, or ORRI, is carved from a leasehold working interest and generally ends when the underlying lease terminates. A working interest carries development and operating cost obligations. It should not be evaluated as though it were a cost-free royalty. The National Association of Royalty Owners explains these ownership distinctions. Ranger’s guides to mineral rights and overriding royalty interests offer additional background.
How a lease creates royalty income
A typical private oil and gas lease grants exploration and development rights under negotiated terms. Those terms address the substances and acreage covered, royalty valuation, duration, pooling authority, and other obligations. Signing a lease does not guarantee that a well will be drilled or that commercial production will follow.
The royalty clause deserves more attention than its percentage alone. It can specify whether payment is based on proceeds, market value, or another measure; identify the valuation location; and address treatment of gas used in operations, processed products, and permissible deductions. Provisions elsewhere in the lease may modify the royalty clause.
Reviewing oil and gas mineral royalties therefore requires reading the whole agreement and any amendments. A short lease memorandum recorded in county records may establish notice of a lease without reproducing its economic terms. Ranger’s oil and gas lease guide explains the broader structure.
If you would like to discuss the mineral or royalty interest described in your records, contact Ranger Land and Minerals for an initial conversation about the information available.
Average oil and gas royalty rates: What the numbers mean
Searches for average oil and gas royalty rates often mix three measurements: the negotiated lease royalty, the owner’s payment decimal, and the dollar amount of a check. These measurements answer different questions. A lease reserving 20% does not mean every person with minerals in the producing unit receives 20% of its sales.
There is no single national average established by the sources used in this guide. Commonly discussed fractions include the examples below. Oklahoma State University Extension identifies 3/16, 1/5, and 1/4 among common royalty fractions in its discussion of energy development and mineral leasing. Those examples are context, not a current market survey.
| Fraction | Percentage | Decimal |
|---|---|---|
| 1/8 | 12.5% | 0.125 |
| 3/16 | 18.75% | 0.1875 |
| 1/5 | 20% | 0.20 |
| 1/4 | 25% | 0.25 |
Geology, competing lease offers, infrastructure, location, and contractual protections influence negotiations. Existing leases generally retain their agreed rates unless law or a valid amendment changes them. A higher percentage can still produce a smaller payment if production, allocated ownership, or the valuation basis differs.
Federal onshore leasing follows a separate framework. The Bureau of Land Management’s leasing-program guidance specifies at least 12.5% for competitive leases and 12.5% for noncompetitive leases under that guidance, while preserving the rates in already-issued leases. These federal terms do not establish average oil and gas royalty rates for private minerals.
How oil and gas royalty payments are calculated
A simplified calculation starts with the royalty-bearing sales value and multiplies it by the owner’s applicable payment decimal. Taxes, permissible deductions, and adjustments then affect the net payment. Actual royalty valuation may require more detail than multiplying a published commodity price by reported production.
Simplified gross royalty = royalty-bearing sales volume × applicable price or value × owner payment decimal.
For a leased mineral interest allocated strictly by acreage, a common starting calculation is net mineral acres divided by total participating unit acres, multiplied by the lease royalty. This assumes the acreage, lease, depths, products, and effective period match and that no separate royalty burden changes the owner’s share.
A hypothetical pooled-unit example
Assume an owner holds 50% of the minerals in an 80-acre tract, and the entire tract participates in a 640-acre unit. The lease reserves a 20% royalty, allocation is strictly by acreage, and no separate royalty conveyance reduces the owner’s retained share.
- Net mineral acres: 80 × 0.50 = 40.
- Unit ownership share: 40 ÷ 640 = 0.0625.
- Royalty payment decimal: 0.0625 × 0.20 = 0.0125.
If the unit sells 10,000 royalty-bearing barrels at an applicable price of $70 per barrel, the sales value is $700,000. Multiplying $700,000 by 0.0125 produces a gross royalty of $8,750 before taxes, allowed deductions, and adjustments. These prices and volumes are illustrative, not forecasts.
The arithmetic shows why a 20% lease royalty can result in a 1.25% unit payment decimal. Do not multiply by the lease royalty again if it is already included in the decimal. Texas A&M’s Real Estate Research Center discusses acreage-based pooling calculations in its lease negotiation guidance.
This formula is not universal. Production-sharing arrangements, cross-unit wells, unit participation schedules, separate royalty deeds, and regulatory orders may require different calculations. NARO’s royalty decimal guide explains important limitations. Net royalty acres also should not be substituted automatically for net mineral acres; see Ranger’s explanation of net mineral acres and net royalty acres.
Are royalties based on gross revenue or net proceeds?
Oil and gas mineral royalties are generally free of the costs of exploring, drilling, completing, and operating a well. That does not make every royalty payment free of every expense. Whether particular post-production charges can reduce a royalty depends on the agreement and applicable law.
Potential post-production items include gathering, compression, treatment, processing, and transportation. Some agreements limit those charges, while others permit certain deductions or establish a valuation point that affects their treatment. Labels such as “gross proceeds” or “no deductions” need to be read with the rest of the contract and relevant state law.
A division order or check stub does not, by itself, establish that a charge is authorized. Compare the payor’s explanation with the governing documents. Also distinguish a reduced sale price from a separately itemized deduction so that the same economic adjustment is not counted twice.
For example, if the hypothetical $8,750 gross royalty above is reduced by $400 in taxes and $350 in authorized charges, the net amount is $8,000. That illustration explains subtraction only; it does not establish the legality of either charge or a representative tax rate.
How to read a royalty statement
Oil and gas royalty payments may arrive by check or direct deposit, but the accompanying statement supplies the accounting detail. Review each product and sales period separately. One deposit may include oil, gas, natural gas liquids, and corrections relating to earlier months.
Start with the property or well identifier, product, sales month, volume, price, and owner decimal. Then distinguish total property sales from the owner’s allocated share. Review production taxes, other deductions, prior-period adjustments, and the final net amount.
Texas law identifies required remittance information in Natural Resources Code Section 91.502. That is a Texas-specific reference; reporting requirements elsewhere may differ.
Unit consistency matters. Mcf means one thousand cubic feet, while MMBtu measures one million British thermal units of energy. Gas volume cannot be multiplied directly by an energy-based price without the appropriate conversion. The U.S. Energy Information Administration explains gas price and heat-content conversions. A national heat-content average is not a substitute for the factor applicable to a particular statement.
When oil and gas royalty payments fall unexpectedly, organize statements by sales month and compare the decimal, volumes, prices, and charges. If unclear ownership records or inconsistent figures are complicating a potential sale or purchase, contact Ranger Land and Minerals to discuss the records involved.
Why royalty income changes over time
A royalty rate can stay constant while income rises or falls. Commodity prices, realized local prices, production volumes, downtime, product mix, and adjustments all affect oil and gas mineral royalties. An unusually large check may include several months of catch-up accounting rather than a lasting increase in production.
Production also tends to decline as reservoir conditions change. EIA explains that horizontal wells can experience substantial production declines, especially compared with conventional vertical wells. The rate varies by reservoir, completion, operating conditions, and well history.
Simple scenarios help isolate the drivers. If royalty-bearing volume falls 20% while price and the ownership decimal remain unchanged, gross royalty also falls 20%. If price rises 10% during that same period, the combined effect is 0.80 × 1.10 = 0.88, or a 12% decline before other changes.
This is why a peak payment should not be treated as a fixed monthly income level. Comparing several periods, identifying one-time adjustments, and separating price changes from volume changes produces a more useful explanation than comparing deposit totals alone.
When are royalties paid, and why can payments stop?
Many payors operate monthly payment cycles, but a payment typically follows the sales period after accounting is completed. Initial payment deadlines, later payment schedules, minimum payment thresholds, and permitted reasons for suspension vary by jurisdiction and contract.
For a clearly labeled state example, the Railroad Commission of Texas royalty FAQ summarizes an initial-payment period of 120 days after the end of the month of first sale. It also describes ongoing periods of 60 days for oil and 90 days for gas after the end of the month of sale, subject to the applicable statutory and contractual conditions.
Payments can be held in suspense because of unresolved title, conflicting ownership claims, missing transfer documentation, or other legally supported conditions. Small balances can also accumulate until a payment threshold is met. A missing deposit therefore does not automatically mean the well stopped producing.
Request a written explanation identifying the affected well, sales periods, reason for withholding, and documents needed. Payment disputes and limitation periods require state-specific review. The Texas commission publishes educational information but states that it does not adjudicate private lease and royalty disputes.
How long do oil and gas mineral royalties last?
There is no dependable universal lifespan. Separate the duration of the mineral interest, the duration of the lease or royalty conveyance, and the economic life of the wells. Each can follow different rules.
A lease commonly includes a primary term for initial development and a secondary term that can continue when qualifying production or another contractual condition maintains it. A primary term of several years is not automatically the maximum royalty-payment period. Penn State Extension explains primary and secondary lease terms.
Some wells remain productive for many years, but their production and commercial viability can change substantially. A shut-in provision may preserve a lease temporarily under specified conditions, sometimes with a separate payment. Its wording must be reviewed before assuming either that the lease ended or that production royalties must continue.
A separately conveyed royalty can be perpetual, limited to a stated term, or dependent on specified conditions. An ORRI generally follows the underlying lease. The NARO mineral and royalty FAQ provides additional context. No general estimate of well life can replace the controlling instruments.
How royalty income is taxed
Oil and gas mineral royalties are generally taxed as ordinary income. For many individuals with nonoperating royalty interests, reporting occurs on Schedule E, but business activities, entity ownership, and operating interests can change the treatment. The IRS Schedule E instructions explain reporting of oil, gas, and mineral royalties and potential depletion deductions.
The cash deposited is not always the gross amount reportable for income-tax purposes. Production taxes withheld from payments and other eligible expenses may require separate accounting. State income taxes, severance or production taxes, and local property taxes are distinct obligations rather than interchangeable names for one tax.
Depletion may allow recovery of an economic investment in qualifying mineral property, but eligibility and limits matter. A percentage sometimes quoted online should not be applied automatically to every receipt. Retain statements, tax forms, acquisition and basis records, and documentation of expenses for review by an appropriate tax professional.
Checking ownership, transfers, and sale offers
Confirming mineral rights and royalty interests begins with the legal description and chain of title. Relevant records can include deeds, reservations, assignments, probate documents, leases, amendments, and pooling instruments. A tax bill or an old check can be useful evidence without proving the full current interest.
After an inheritance or transfer, recorded ownership and the payor’s owner records may need separate attention. NARO’s mineral title search guide explains the role and limitations of public-record research. Keep the documents organized by tract, county, depth or formation, and effective date.
Deed fractions also require care. A fixed fraction of production differs from a floating fraction of the lease royalty. In a simplified unpooled example, a fixed 1/16 is 6.25% of production, while one-half of a 20% lease royalty is 10%. Actual instruments must be interpreted as a whole under applicable law. The Texas Supreme Court discusses the distinction in U.S. Shale Energy II v. Laborde Properties.
A proposed purchase price should be evaluated against the exact rights conveyed, existing income, production decline, lease terms, and the uncertainty of additional development. NARO’s valuation guide explains why forecasts and assumptions matter. Ranger’s selling mineral rights guide offers related background. Neither an income multiple nor an acreage price is a universal appraisal method.
Frequently asked questions
Are mineral rights and royalty interests the same?
No. Mineral rights may include development rights, leasing authority, and rights to payments. A royalty interest provides a specified share of production or its value without necessarily including those other rights. The deed, lease, or assignment determines what was retained or transferred.
What are average oil and gas royalty rates?
There is no single national average established by the sources used here. Commonly discussed lease fractions include 12.5%, 18.75%, 20%, and 25%, but an applicable rate depends on the contract and legal framework. The lease percentage also differs from an individual owner’s well-payment decimal.
How are oil and gas royalty payments calculated?
A simplified gross royalty equals royalty-bearing sales volume multiplied by the applicable price or value and the owner’s payment decimal. Taxes, permitted deductions, and adjustments affect the net payment. Ownership documents, allocation provisions, and lease valuation terms determine the correct inputs.
Do royalty owners pay drilling costs?
Ordinary royalty interests generally do not bear exploration, drilling, completion, or operating costs. Taxes and certain post-production charges may still affect payments when authorized by the governing agreement and law. A working interest carries different cost obligations and should be evaluated separately.
Why did a royalty payment decrease?
Possible causes include lower production, lower realized prices, downtime, changed product mix, authorized deductions, and prior-period accounting corrections. Compare statements for the same sales periods and verify the ownership decimal before attributing the change to one cause.
Do royalties end when the lease’s primary term expires?
Not necessarily. Qualifying production or another lease condition can maintain a lease beyond its primary term. A separately conveyed royalty may have its own duration. The lease, conveyance, and applicable law determine whether the interest and payment obligation continue.
Understanding the full royalty picture
Oil and gas mineral royalties are easier to evaluate when ownership, lease percentage, payment decimal, sales value, and deductions are considered separately. That approach explains both the amount paid and the uncertainty surrounding future income.
Before a sale or purchase, connect the records to the rights being transferred and the assumptions behind the proposed value. Contact Ranger Land and Minerals today to discuss your mineral or royalty interest and available transaction opportunities.